
Latest
Attention Realtors: Terms Protect Your Price in Baton Rouge
A carry-back is a better concession than a price cut because the seller protects their equity and earns interest on the balance.
Private Financing Specialists
Latest
A carry-back is a better concession than a price cut because the seller protects their equity and earns interest on the balance.
When affordability drops and home prices remain steady, a bond for deed can bridge the gap and keep Northshore transactions moving forward.
Fannie and Freddie accepting VantageScore 4.0 lets buyers refinance out of seller financing, giving note holders a complete win with an early full payoff.
How a six-month climb in interest rates impacts a typical $250,000 Northshore house payment and why a Bond for Deed offers a necessary bridge.
A fixed Bond for Deed payment set directly by the parties offers insulation the traditional bank market cannot match after a rate hike.
After storms like Bertha and Edouard, the seller-financed deals that stay clean have a third party keeping records and taking payments.
When housing inventory tightens, sellers who carry the note and buyers with a strong down payment bypass conventional mortgage barriers.
Recent fire rating upgrades in St. Tammany Parish lower property insurance premiums, creating compounding savings for buyers in seller-financed deals.
When Louisiana home appreciation stalls, sellers can move property and maintain their asking price by competing on terms traditional banks cannot match.
A complete third-party payment history is the definitive record that settles questions between buyers and sellers.
When high rates and rigid underwriting push conventional buyers out of the market, a well-structured Bond for Deed gives sellers a way to close the deal.
While national average mortgage rates drift higher, an installment schedule agreed to at closing provides absolute certainty for buyers and sellers.
A weak tropical storm is a reminder that flood coverage, not wind, is the gap that sinks a private sale. Put proof of coverage on the closing checklist.
Individual sellers can secure professional record-keeping, escrow handling, and neutral payment administration for a single loan at a low flat fee.
Federal supply measures cannot solve the massive insurance premiums killing local deals, but a properly serviced Bond for Deed can hold the transaction together.
Inland flooding from Tropical Storm Arthur shows why private real estate sellers must require buyers to maintain active flood insurance.
Self-directed IRA custodians hold the asset, but independent escrow agents must collect, track, and disburse the monthly payments.
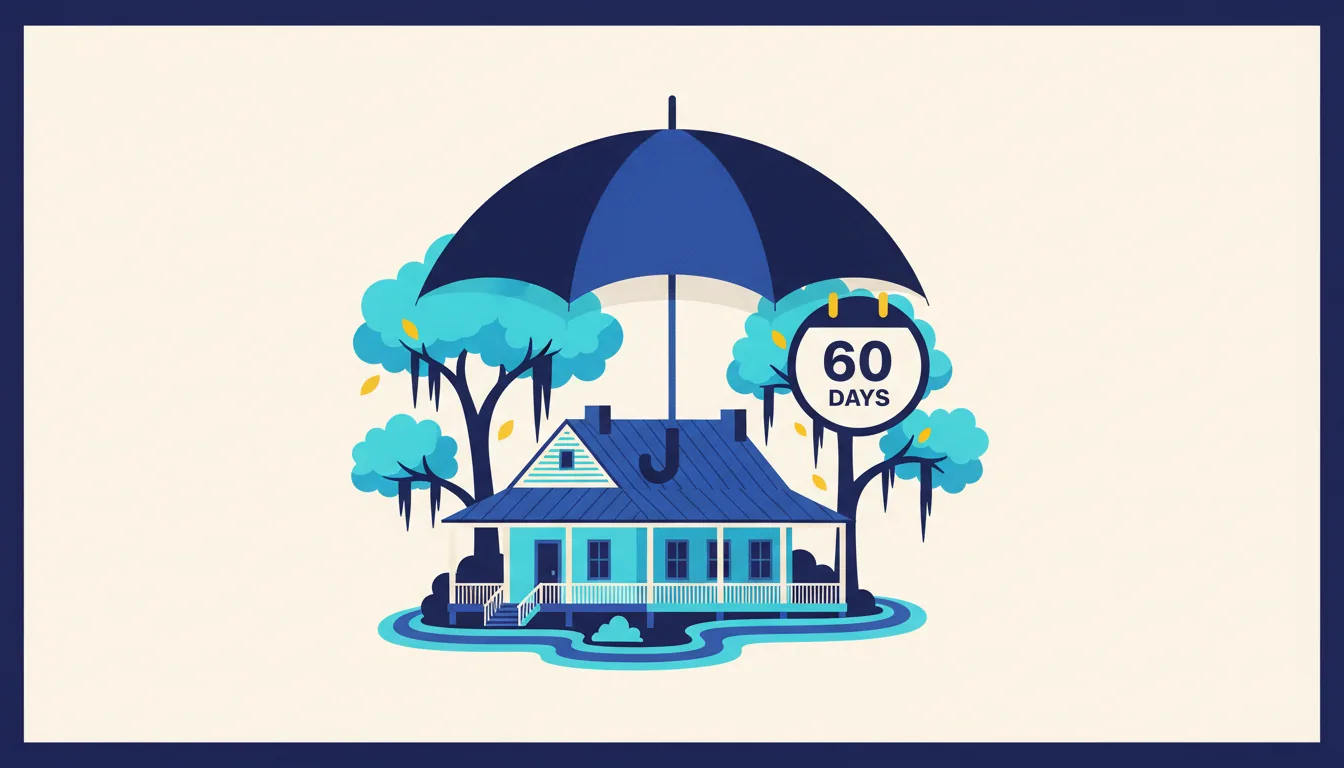
Act 848 doubles the property insurance cancellation notice to 60 days, giving buyers and sellers vital time to protect their real estate collateral.
Flexibility
One of the most frustrating costs for many homebuyers using conventional financing is Private Mortgage Insurance, commonly known as PMI.
Louisiana’s new Act 807 imposes the kind of third-party escrow discipline on wholesalers that Bond for Deed has utilized for decades.
A flat monthly servicing fee offers property sellers better long-term value than a schedule filled with per-item administrative charges.
Flexibility
One of the most misunderstood features of a Bond for Deed transaction is that the buyer receives possession and the economic benefits of homeownership, while legal title remains with the seller until the contract is paid off or refinanced.
Myths
A mortgage denial is usually a lending-box problem, not a character judgment, making Bond for Deed a practical alternative for capable Louisiana buyers.
Flexibility
In today’s real estate environment, many borrowers struggle to bring enough cash to the closing table.
Facts
Licensed escrow agents replaced traditional banks in servicing bond for deed agreements, creating a more specialized process for title companies.
The labels blur on seller-financed deals. Choose between a Bond for Deed, lease purchase, or installment option based on who holds title and equity.
Myths
A tenant with a purchase option builds no equity in the property, making a lease purchase a weaker position than a Bond for Deed.
One common misconception is that sellers save money by collecting private mortgage payments directly.
Facts
One of the most common questions asked by bond for deed sellers is: “What happens if the buyer stops making payments?”
Flexibility
A Bond for Deed does not bypass insurance, but structuring the transaction properly frees up the cash buyers need for high first-year premiums.
Facts
A question that occasionally arises from both buyers and sellers is: “What happens if one of the parties dies?”
With most homeowners locked into low rates, free and clear sellers are the natural solution for buyers needing seller financing to bypass the banks.
Because a bond for deed seller retains legal title, uninsured flood damage represents a direct financial risk to their collateral.
Facts
A properly drafted bond for deed contains a feature that many people find counterintuitive: a special mortgage.
Conventional lending is shutting out younger buyers, but sellers who offer a Bond for Deed or private mortgage can set their own down payment rules.
Facts
Another common concern surrounding bond for deed transactions is how they are treated in the event of a bankruptcy, whether filed by the seller or the buyer.
Facts
One of the most common and understandable questions from bond for deed purchasers is this: “If the title stays in the seller’s name, what happens if the seller later has a lien or judgment filed against them?”
Facts
In a bond for deed, it is often said that the purchaser takes on both the burdens and the benefits of homeownership.
Facts
A very common misconception about bond for deeds is the belief that their terms must match—or somehow track—the terms of an existing mortgage.
Facts
A bond for deed operates in many ways like a traditional mortgage loan.
Myths
In our ongoing series debunking myths about Bond for Deed financing, today’s topic is especially timely given the current federal government shutdown and its ripple effects across the real estate industry.
Myths
In our continuing series on Bond for Deed financing myths, we’re tackling a scenario that many real estate agents encounter—and often walk away from prematurely: Myth #11: “If the Seller Has No Equity, There’s No Way to Earn a Commission”
Myths
In our ongoing series debunking myths about Bond for Deed financing, we’re highlighting a powerful—but often overlooked—benefit for buyers who want to build equity faster and avoid unnecessary costs.
Myths
In our continuing series on Bond for Deed financing myths, we’re diving into a misconception that can lead to costly mistakes and missed opportunities for both buyers and sellers: Myth #9: “Anyone Can Prepare a Bond for Deed Agreement”
Myths
In our ongoing series debunking common myths about Bond for Deed financing, today we’re tackling a misconception that can cost buyers and sellers real money: Myth #8: “Bond for Deed Doesn’t Help with Closing Costs”
Myths
One of the most common misconceptions we hear from real estate agents is that Bond for Deed transactions are difficult to execute.
Myths
When discussing Bond for Deed transactions—especially those involving an underlying mortgage—a common myth surfaces: “Only a Louisiana-licensed bank can service a Bond for Deed.”
Myths
One persistent myth surrounding Bond for Deed transactions is the belief that if there is an existing mortgage on the property, the seller must get approval from the mortgage holder before entering a Bond for Deed agreement.
Myths
One of the most persistent myths surrounding Bond for Deed financing is the idea that buyers who use this method are more likely to default on their payments.
Myths
One of the most common misconceptions about Bond for Deed financing is that it’s only used by buyers with poor credit.
Myths
When it comes to creative financing in real estate, few tools are as misunderstood—and underutilized—as the Bond for Deed.
In today’s investment environment sellers who have no immediate need for the cash they receive out of the sale of their home are giving more and more consideration to providing seller financing, particularly to buyers with material down payments.
Your state now requires a servicer of a note which is secured with residential real estate, where the servicer does not have a 100% interest in the note, to be licensed by the state.
Like most things in life you get what you pay for when you engage a company to service your note.
A funny thing happened on the way to the government bailout of the “too big to fail” mortgage lenders.
June 30, 2016 represents year one since the date set by the Louisiana Office of Financial Institutions for all mortgage servicers in Louisiana to become licensed for the specific purpose of servicing residential mortgages.
Sellers often assume that an individual acquiring a property under a BFD must have bad credit.
We regularly hear, “If there is a mortgage on the property you need the mortgage holder’s approval to do a BFD”.
Mortgage Not Assumable—Use a Bond for Deed whenever the existing mortgage is not assumable.
Simply put a Bond For Deed is a form of Seller Financing. It is a contract to sell Real Estate in which the purchase price is paid in installments and title is transferred after the payments are made in full.

NMLS #1385244
The leader since 1985, Escrow Services Inc. has the highest standards in the industry. While other contract service companies will collect & disburse payments for almost any contract, Escrow Services Inc. reviews documents to ensure financial and legal integrity begin before the contract is signed.
Useful Links
Copyright © 2025 Escrow Services Inc. All Rights Reserved | Website by Smart Web Ninja.