Bond for Deed Myth #10: “It Doesn’t Help Buyers Build Equity Faster”
In our ongoing series debunking myths about Bond for Deed financing, we’re highlighting a powerful—but often overlooked—benefit for buyers who want to build equity faster and avoid unnecessary costs.
In our ongoing series debunking myths about Bond for Deed financing, we’re highlighting a powerful—but often overlooked—benefit for buyers who want to build equity faster and avoid unnecessary costs.
Myth #10: “Bond for Deed Doesn’t Help Buyers Build Equity Faster”
This myth stems from the assumption that Bond for Deed is just a workaround for buyers who can’t qualify for conventional financing. But Bond for Deed can be a strategic tool that helps buyers build equity more efficiently—especially when compared to traditional mortgages burdened by Private Mortgage Insurance (PMI).
🛡️ The Problem with PMI
In conventional financing, buyers who don’t have a sufficient down payment—typically 20%—are required to pay PMI. This insurance protects the lender, not the buyer, and it can add hundreds of dollars to the monthly payment.
Here’s the catch: PMI doesn’t build equity. It’s a sunk cost that continues until the buyer reaches a certain loan-to-value ratio, which can take years. In many cases, PMI lasts for the first 7–10 years of the loan, costing buyers thousands of dollars with no ownership benefit.
🔄 How Bond for Deed Changes the Game
Bond for Deed offers a unique opportunity to redirect what would have been PMI payments toward principal reduction. This means buyers can:
- Avoid PMI entirely
- Apply extra monthly payments directly to principal
- Shorten the amortization period from 30 years to 22–23 years
- Save tens of thousands of dollars in interest over the life of the loan
This is especially valuable for buyers who are financially stable enough to make consistent payments but don’t meet the strict criteria for conventional loans.
🛣️ A Smarter Path to Conventional Financing
Let’s say a buyer enters into a Bond for Deed agreement with a 4–5 year balloon term. During that time, they make regular payments—plus additional principal payments that would have otherwise gone toward PMI.
By the end of the balloon period, the buyer has:
- Built substantial equity
- Reduced the overall loan amount
- Improved their loan-to-value ratio
- Positioned themselves to refinance into a conventional loan without PMI
This isn’t just a workaround—it’s a financial strategy that benefits the buyer long-term.
📋 Real-World Example
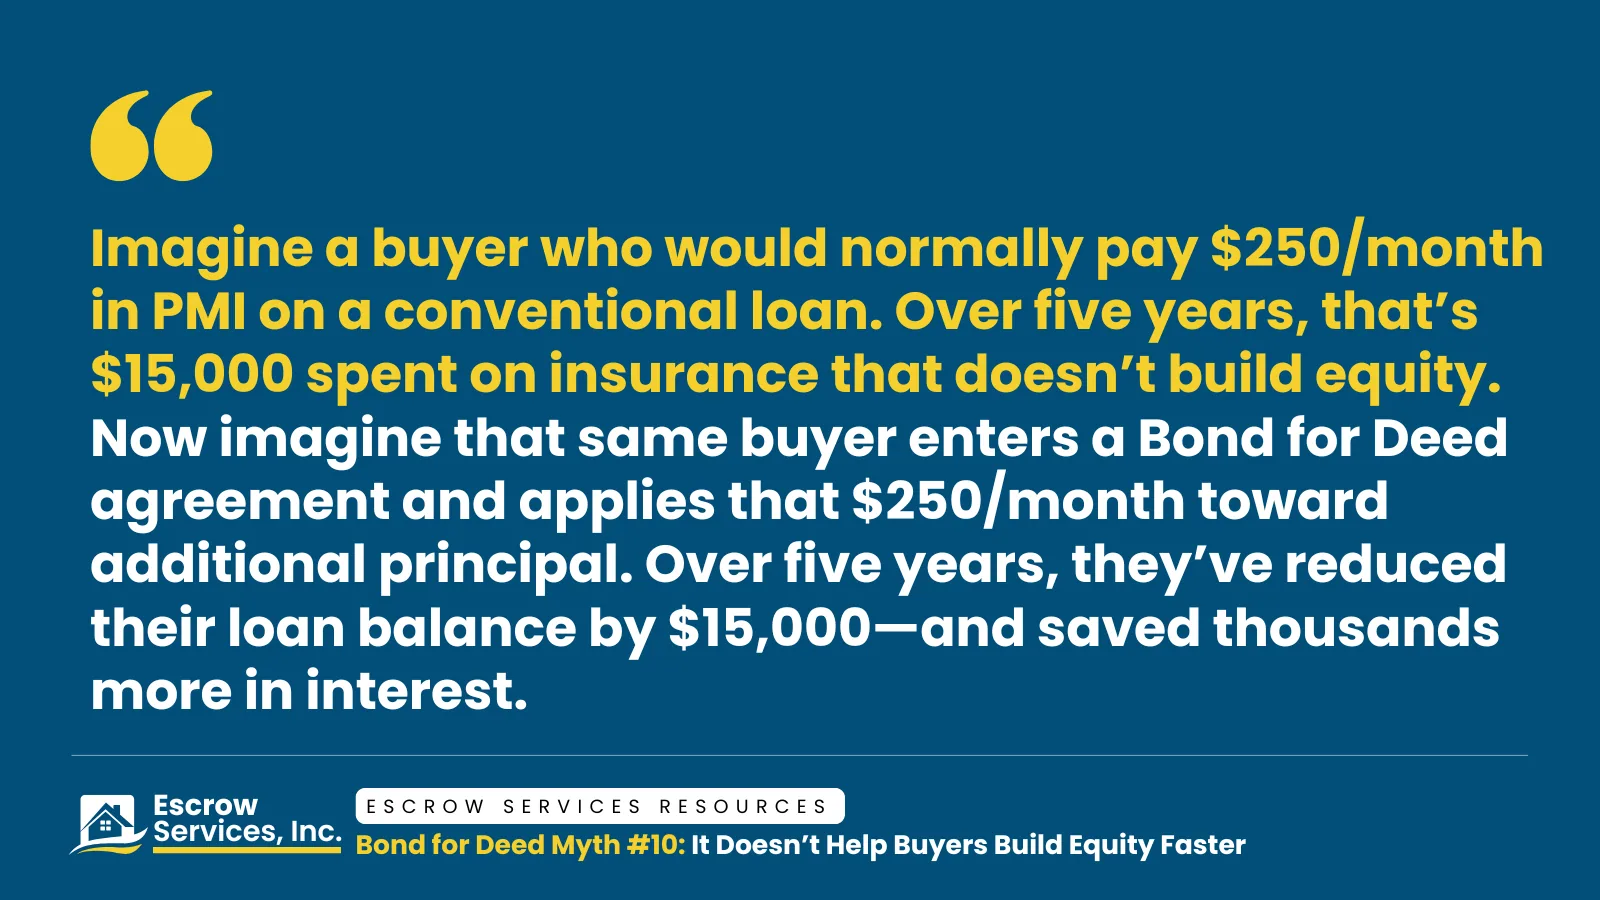
Imagine a buyer who would normally pay $250/month in PMI on a conventional loan. Over five years, that’s $15,000 spent on insurance that doesn’t build equity.
Now imagine that same buyer enters a Bond for Deed agreement and applies that $250/month toward additional principal. Over five years, they’ve reduced their loan balance by $15,000—and saved thousands more in interest.
When it’s time to refinance, they’re in a stronger financial position, with a lower loan amount and no PMI requirement.
🎓 Why Real Estate Agents Should Pay Attention
For agents, understanding this nuance can be a meaningful change. When buyers are struggling to qualify for conventional loans due to PMI requirements, Bond for Deed offers a flexible alternative that:
- Keeps deals alive
- Helps buyers build equity faster
- Positions clients for future success
- Creates more opportunities for closings and commissions
Smart agents know that it’s not just about getting the deal done—it’s about helping clients make financially sound decisions that benefit them long-term.
📝 Structuring the Deal Correctly
Of course, the success of this strategy depends on how the Bond for Deed is structured. That’s where working with an experienced closing agent becomes critical.
At Escrow Services, we help buyers and sellers:
- Set realistic balloon terms
- Structure payments to maximize equity growth
- Avoid common pitfalls that can derail future refinancing
- Ensure the agreement supports long-term financial goals
We don’t just prepare documents—we help craft deals that work.
💡 Bottom Line
Bond for Deed isn’t just a tool for buyers who can’t qualify for a mortgage—it’s a strategic pathway to faster equity, lower costs, and smarter refinancing.
By avoiding PMI and applying those funds toward principal, buyers can shorten their loan term, save thousands, and position themselves for a stronger financial future.
📣Want to explore how Bond for Deed can help your clients build equity faster?
📞 Call us at (985) 626-3727
📧 Email: service@escrowserviceinc.com
Stay tuned for Myth #11 in our series, where we’ll continue to uncover the hidden advantages of Bond for Deed financing.