
Northshore Prices Held While Affordability Fell
When affordability drops and home prices remain steady, a bond for deed can bridge the gap and keep Northshore transactions moving forward.

When affordability drops and home prices remain steady, a bond for deed can bridge the gap and keep Northshore transactions moving forward.
Fannie and Freddie accepting VantageScore 4.0 lets buyers refinance out of seller financing, giving note holders a complete win with an early full payoff.
How a six-month climb in interest rates impacts a typical $250,000 Northshore house payment and why a Bond for Deed offers a necessary bridge.
A fixed Bond for Deed payment set directly by the parties offers insulation the traditional bank market cannot match after a rate hike.
After storms like Bertha and Edouard, the seller-financed deals that stay clean have a third party keeping records and taking payments.
When housing inventory tightens, sellers who carry the note and buyers with a strong down payment bypass conventional mortgage barriers.
Recent fire rating upgrades in St. Tammany Parish lower property insurance premiums, creating compounding savings for buyers in seller-financed deals.
When Louisiana home appreciation stalls, sellers can move property and maintain their asking price by competing on terms traditional banks cannot match.
When high rates and rigid underwriting push conventional buyers out of the market, a well-structured Bond for Deed gives sellers a way to close the deal.
While national average mortgage rates drift higher, an installment schedule agreed to at closing provides absolute certainty for buyers and sellers.
Federal supply measures cannot solve the massive insurance premiums killing local deals, but a properly serviced Bond for Deed can hold the transaction together.
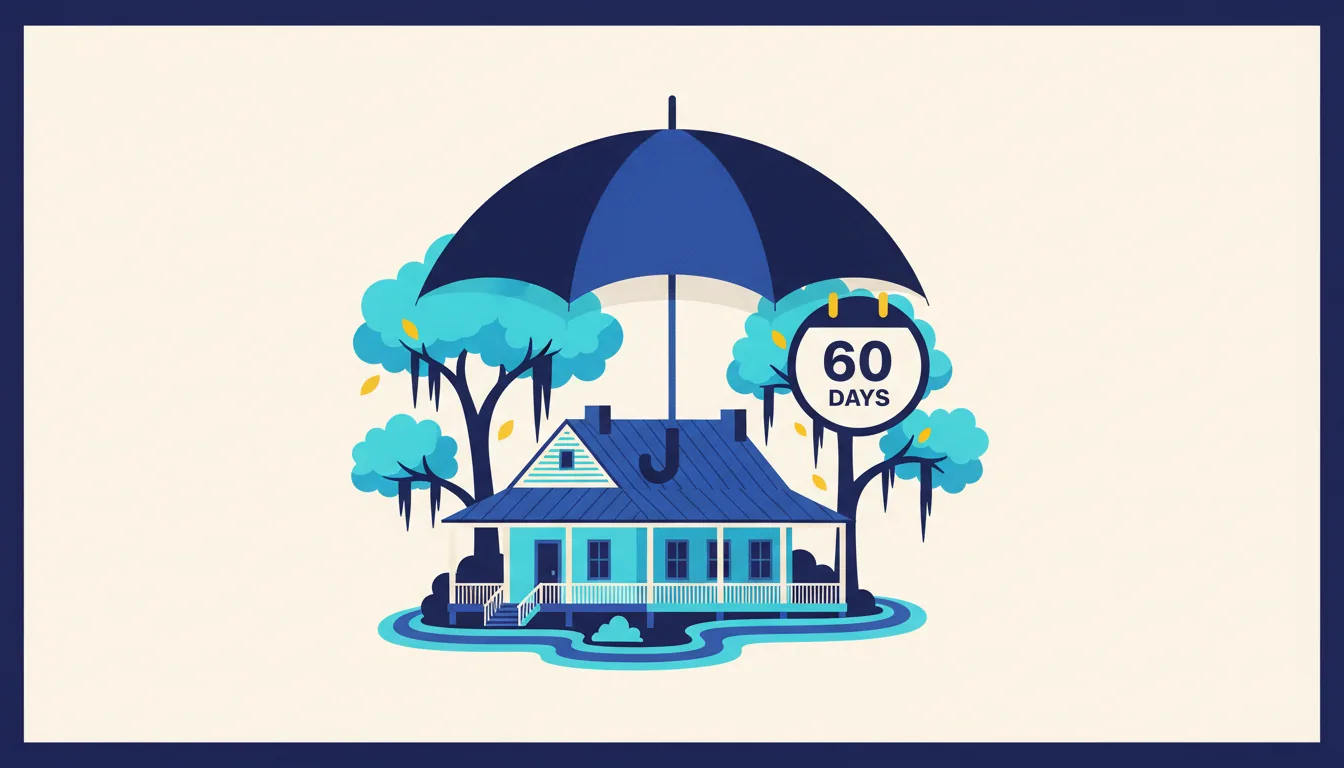
Act 848 doubles the property insurance cancellation notice to 60 days, giving buyers and sellers vital time to protect their real estate collateral.
Louisiana’s new Act 807 imposes the kind of third-party escrow discipline on wholesalers that Bond for Deed has utilized for decades.
Myths
A mortgage denial is usually a lending-box problem, not a character judgment, making Bond for Deed a practical alternative for capable Louisiana buyers.
Facts
Licensed escrow agents replaced traditional banks in servicing bond for deed agreements, creating a more specialized process for title companies.
The labels blur on seller-financed deals. Choose between a Bond for Deed, lease purchase, or installment option based on who holds title and equity.
Myths
A tenant with a purchase option builds no equity in the property, making a lease purchase a weaker position than a Bond for Deed.
Flexibility
A Bond for Deed does not bypass insurance, but structuring the transaction properly frees up the cash buyers need for high first-year premiums.
With most homeowners locked into low rates, free and clear sellers are the natural solution for buyers needing seller financing to bypass the banks.
Because a bond for deed seller retains legal title, uninsured flood damage represents a direct financial risk to their collateral.
Conventional lending is shutting out younger buyers, but sellers who offer a Bond for Deed or private mortgage can set their own down payment rules.

NMLS #1385244
The leader since 1985, Escrow Services Inc. has the highest standards in the industry. While other contract service companies will collect & disburse payments for almost any contract, Escrow Services Inc. reviews documents to ensure financial and legal integrity begin before the contract is signed.
Useful Links
Copyright © 2025 Escrow Services Inc. All Rights Reserved | Website by Smart Web Ninja.